Trump Signs New Housing Executive Order to Reduce Mortgage and Homeownership Costs
Trump Signs New Housing Executive Order to Reduce Mortgage and Homeownership Costs
There is potentially encouraging news for American homebuyers and homeowners.
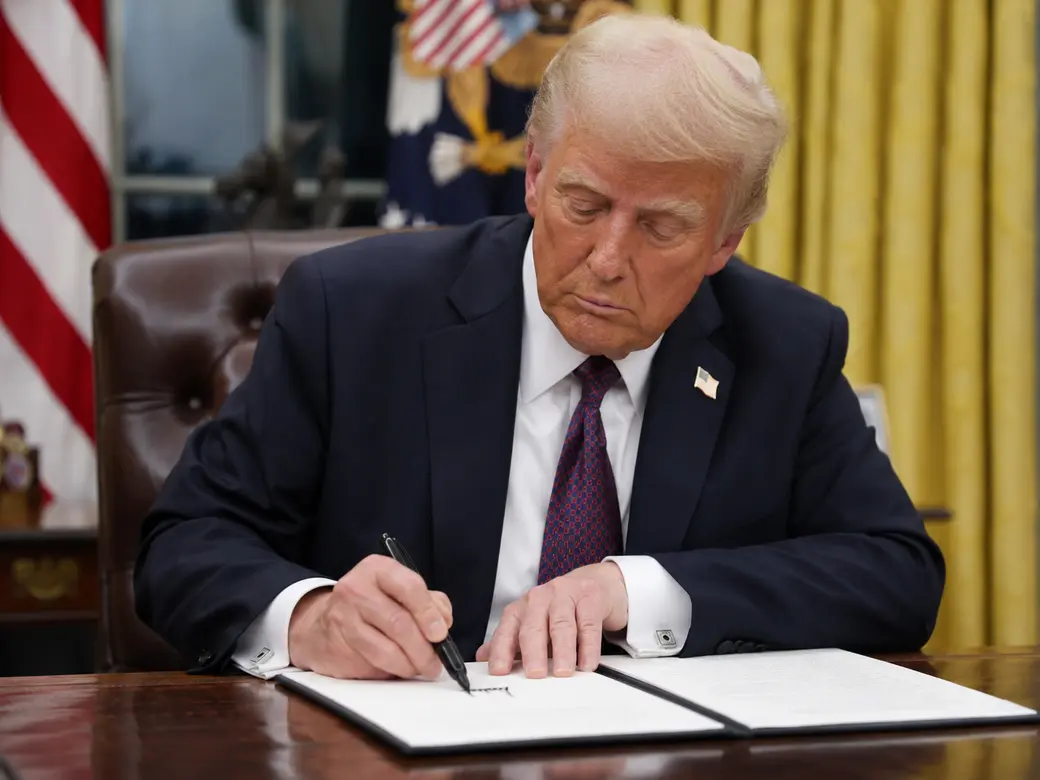
On October 22, 2026, President Donald Trump signed a new executive order titled “Decreasing Housing Costs for the American People.”
The order is aimed at reducing several expenses connected with buying, refinancing, and owning a home.
Among the initiatives are efforts to make mortgage insurance easier to cancel for certain future borrowers, reduce some refinancing costs, lower interest rates on specific government direct loans, and encourage more affordable factory-built housing.
These changes will not all take effect immediately, and not every homeowner or buyer will qualify.
Still, the order could eventually create meaningful savings for eligible borrowers.
Here is what homebuyers and homeowners should know.
Mortgage Insurance Could Become Easier to Cancel
One of the biggest parts of the executive order involves private mortgage insurance, commonly known as PMI.
PMI is generally required on certain conventional mortgages when the borrower puts less than 20% down. It protects the lender if the borrower stops making payments, but it adds another expense to the homeowner's monthly mortgage bill.
Under current federal rules, qualifying homeowners can generally request PMI cancellation when their loan balance reaches 80% of the home's original value. Automatic cancellation is required for many qualifying loans when the balance is scheduled to reach 78%, assuming applicable requirements are met.
The new executive order directs the Federal Housing Finance Agency, or FHFA, to establish a pilot program through Fannie Mae and Freddie Mac, subject to required determinations.
The program would use automated property valuations and other available information to identify qualifying homeowners who have built enough equity to potentially remove mortgage insurance.
Instead of relying entirely on the homeowner to start the process, mortgage servicers could proactively identify and notify eligible borrowers.
For qualifying homeowners, that could eventually mean less paperwork and an opportunity to stop paying PMI sooner.
However, there is an important limitation:
The proposed pilot would apply only to mortgages originated after the pilot program is established.
The executive order does not immediately cancel mortgage insurance for current homeowners.
Eligibility would also depend on factors such as equity, payment history, financial safety standards, and final program requirements.
Refinancing Could Become Less Expensive
The order also focuses on reducing some of the costs associated with refinancing a mortgage.
Refinancing allows homeowners to replace an existing mortgage with a new loan, potentially to obtain a different interest rate, monthly payment, or loan term.
But refinancing can involve significant upfront expenses, including appraisal costs, lender fees, and title-related charges.
The executive order directs the FHFA, subject to required determinations, to expand an existing title acceptance pilot into a nationwide program through Fannie Mae and Freddie Mac.
Under the proposed approach, some qualifying refinance transactions could use approved automated title-risk assessments instead of traditional lender's title insurance.
The FHFA is also directed to consider changes such as:
-
Expanding eligibility for certain refinance transactions
-
Reducing unnecessary appraisal requirements
-
Simplifying income reverification and documentation
-
Reducing or eliminating certain loan-level pricing adjustments and fees
The order also requires resulting program savings to be passed on to borrowers.
For qualifying homeowners, these changes could reduce some of the upfront expenses associated with refinancing.
However, this does not eliminate refinancing costs for everyone.
It also does not eliminate traditional title insurance requirements for every home purchase.
Actual savings will depend on the final rules, borrower eligibility, lender participation, and the specific loan.
Certain USDA and VA Direct Loans Could Receive Lower Rates
Another provision focuses on specific home loans made directly by the federal government.
The executive order directs the U.S. Department of Agriculture and the Department of Veterans Affairs to reduce interest rates on certain single-family direct loans, consistent with applicable law and available funding.
This distinction is important.
Not every USDA or VA mortgage is a direct government loan.
Many VA mortgages, for example, are issued by private lenders and guaranteed by the federal government. Those are different from loans issued directly by the VA.
The executive order therefore does not automatically lower mortgage rates for every VA borrower.
It also does not create a universal rate reduction for all FHA, USDA, conventional, or other mortgages.
Borrowers will need to review future agency guidance and the requirements of their specific loan program to determine whether they qualify.
The Order Also Targets the Cost of Building Homes
The executive order does not focus only on mortgages.
It also creates a Task Force on Manufactured Housing Innovation, led jointly by the Department of Housing and Urban Development and the FHFA.
The task force will examine ways to support more efficient production of manufactured and other factory-built housing.
Its work will include studying ways to:
-
Simplify certain approvals
-
Reduce unnecessary regulatory duplication
-
Improve coordination between federal agencies
-
Encourage modern construction methods
-
Support more efficient housing production
Factory-built housing can sometimes reduce construction time and certain production expenses compared with traditional on-site building.
The task force is required to submit recommendations within 180 days of the executive order.
This could eventually help expand more affordable housing options.
However, the executive order does not immediately change local zoning rules or guarantee that new homes will become less expensive.
Any impact on housing supply and prices will depend on future recommendations and implementation.
Will Mortgage Payments Drop Immediately?
For most homeowners and buyers, no immediate across-the-board mortgage payment reduction was announced.
As of October 23, 2026:
-
The mortgage insurance initiative still requires a pilot program to be established
-
The refinancing changes require additional FHFA action
-
The USDA and VA rate provision applies only to certain direct government loans
-
The manufactured housing task force still needs to develop its recommendations
There is no universal mortgage rate reduction for all American homebuyers under the executive order.
The order also does not guarantee that home prices will fall.
Instead, it targets specific expenses that contribute to the cost of financing, refinancing, and producing housing.
For borrowers who eventually qualify, those individual savings could still be meaningful.
Who Could Benefit?
The potential benefits depend on which part of the executive order applies.
Future Conventional Mortgage Borrowers
Borrowers whose mortgages qualify for the future Fannie Mae and Freddie Mac pilot may eventually have a more streamlined process for removing PMI after building sufficient equity.
Homeowners Who Want to Refinance
Qualifying homeowners could benefit from lower title-related expenses, reduced documentation requirements, fewer appraisal requirements in certain cases, or other lower refinancing costs.
Certain USDA and VA Direct-Loan Borrowers
Borrowers using qualifying loans made directly by these federal agencies could benefit from lower interest rates once the directives are implemented.
Future Buyers of Factory-Built Homes
Buyers could benefit over the longer term if future policies help reduce production costs or increase the availability of manufactured and other factory-built housing.
Not everyone will qualify for every benefit.
The final impact will depend on how each agency implements the executive order.
What Should Buyers and Homeowners Do Now?
The announcement is worth following, but consumers should avoid making financial decisions based on benefits that have not yet been implemented.
If you currently pay PMI, contact your mortgage servicer and ask about the cancellation options already available under your existing loan.
If you are thinking about refinancing, compare the rates, closing costs, monthly savings, and break-even period available today rather than assuming future programs will automatically provide a better deal.
If you are considering VA or USDA financing, confirm whether the loan you are exploring is a direct government loan or a privately issued government-backed mortgage.
And if you are preparing to buy a home, continue evaluating financing based on the terms available today.
The executive order may create additional opportunities in the future, but a home purchase should still make sense based on confirmed numbers.
Frequently Asked Questions About the New Housing Executive Order
What is Trump's new housing executive order about?
Signed on October 22, 2026, the executive order is intended to reduce certain costs associated with homeownership through mortgage insurance reforms, lower refinancing expenses, changes to some government direct-loan interest rates, and initiatives involving factory-built housing.
Will PMI automatically disappear for homeowners?
No. The order directs the creation of a pilot program for qualifying mortgages originated after the pilot is established. Existing homeowners do not automatically have their mortgage insurance canceled because of the executive order.
Does the executive order lower mortgage rates for everyone?
No. The interest-rate provision applies to certain USDA and VA direct loans, subject to applicable laws, funding, and agency implementation. It does not create a lower mortgage rate for every borrower.
Could refinancing become cheaper?
Potentially. The order directs the FHFA to expand certain title alternatives and consider reducing appraisal, documentation, pricing, and other expenses for qualifying refinance transactions.
Does the order eliminate homeowners insurance?
No. Mortgage insurance and homeowners insurance are different.
The PMI initiative involves insurance that protects mortgage lenders against borrower default. It does not eliminate homeowners insurance, wind coverage, or flood insurance.
Will the executive order make home prices fall?
Not necessarily. The order includes initiatives designed to reduce certain financing and housing-production costs, but it does not guarantee lower home prices. Housing prices will continue to depend on factors such as supply, demand, financing conditions, location, and the broader economy.
When will these changes take effect?
There is no single implementation date for every provision.
Several initiatives require additional action by federal agencies, while the manufactured housing task force has 180 days to submit its recommendations.
What This Could Mean for Future Homebuyers
The October 22, 2026 executive order represents an effort to address several expenses that make buying and owning a home more costly.
Easier PMI cancellation, lower refinancing expenses, reduced rates for certain direct government loans, and efforts to expand lower-cost housing could eventually benefit eligible Americans.
But the details matter.
Many of these programs still need to be developed or implemented before consumers can use them.
For now, buyers should continue evaluating homes based on the financing, monthly payment, insurance, taxes, and other ownership costs available today.
At The Suncoast Group, we help buyers understand the complete financial picture when purchasing a home, including how financing conditions can affect affordability and buying power.
As these housing initiatives develop, staying informed can help buyers better understand which opportunities may apply to them.
The Suncoast Group powered by LPT Realty
Investors & Realtors®
941-413-1515
Source: The White House, “Decreasing Housing Costs for the American People,” October 22, 2026
https://www.whitehouse.gov/presidential-actions/2026/10/decreasing-housing-costs-for-the-american-people/
Categories
- All Blogs (20)
- Buyer Resources (6)
- florida (3)
- Home Buying Tips (10)
- Home Selling Tips (1)
- homes for sale (1)
- Local Area Guides (3)
- Market Trends (2)
- Millennials & Gen Z (1)
- new home (1)
- new listing (1)
- personal finance (2)
- port charlotte (1)
- real estate (6)
- Real Estate News (1)
- Relocation (3)
- Retirement (1)
- southwest florida (4)
- Waterfront Homes (1)
Recent Posts
"Molly's job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "
GET MORE INFORMATION